⏱ 2 min read
Long-end Treasury yields hit highs since 2004 as futures price another hike in October and potentially one in January; the higher-for-longer risk is moving from rhetoric into market pricing.
The Federal Open Market Committee raised its benchmark rate by 25 basis points to a 3.75%–4% target range, while a Fed official referred to as ‘Paulson’ warned that underlying inflation remains elevated and that “modest further tightening may be warranted” if conditions evolve as expected.
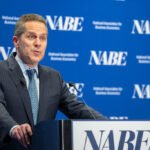
In prepared remarks at a fintech conference, she said underlying inflation is still running around 2.5%–3%, “well above our 2% target,” and that this gap has shown “little signs of closing.” She added that inflation has held higher even outside of oil supply shocks and tariffs. Beyond prices, she described economic output as “solid” and the labor market as “holding steady.”
Markets have moved to price more tightening. According to the CME Group’s FedWatch tool, traders see a 64% chance of another hike in October and expect another move in January. Longer-duration Treasury yields have risen to levels last seen in 2004. Separately, New York Fed President John Williams said it is “reasonable” to expect another hike before year-end.
Why it matters for markets
Rising long-end yields tighten financial conditions by lifting discount rates and financing costs. Analysis: that mechanism is typically a headwind for duration-sensitive assets—including growth equities and portions of crypto—irrespective of whether the next Fed move is a single 25 bp step. The futures profile (including an implied funds rate near 4.8% by end-2027, per the supplied material) is consistent with a higher-for-longer regime, which can weigh on risk appetite until core inflation decisively trends toward target.
Limitations
Key details in the supplied material are incomplete. The identity and role of ‘Paulson’ are not specified, nor is the specific measure underlying the 2.5%–3% inflation estimate. The precise Treasury tenor referenced for the “since 2004” comparison is also not named. Futures probabilities can shift quickly with new data.
What to watch next
– October and January meeting odds on CME FedWatch for confirmation or reversal of the added hikes now priced.
– Upcoming core inflation and labor data to see whether the inflation gap to 2% begins to narrow.
– The trajectory of longer-duration Treasury yields, which are currently doing much of the tightening beyond the policy rate itself.
This content is for informational purposes only and does not constitute financial advice.
🧠 HafidWatch Take
The key signal isn’t the 25 bp hike but the rise in long-end Treasury yields to levels last seen in 2004, alongside futures pricing in more tightening and a higher-for-longer rate path. With ‘Paulson’ noting that underlying inflation hasn’t improved much, the burden of proof shifts to upcoming economic data. For risk assets, including crypto, elevated real discount rates from long-term yields compress valuations and raise the hurdle for new risk-taking, even if the Fed’s moves are modest. The critical factor to watch is whether core inflation metrics clearly downshift to narrow the gap to 2%; until then, it’s the yield curve—not the latest hike—that’s driving tightening.
Daily crypto intelligence. Before the market opens.
Including the Divergence Index — the sentiment gap no other newsletter tracks. Free, every morning at 7:30am ET.
✓ Free forever · ✓ No spam · ✓ 50+ sources monitored